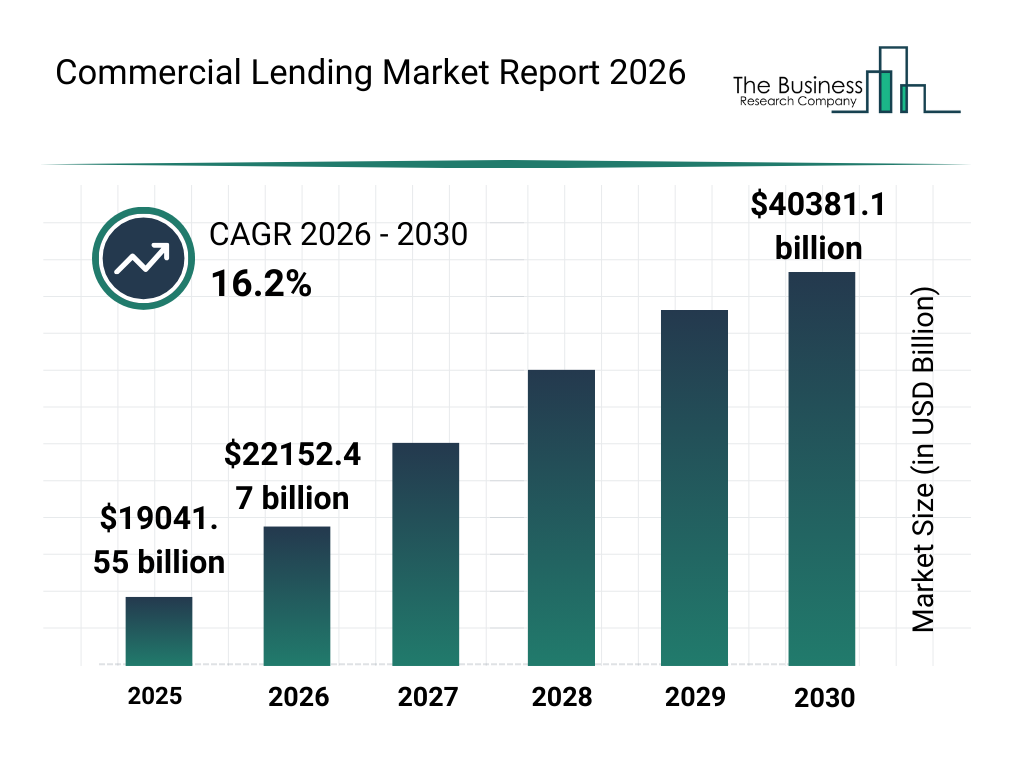
what are the top commercial lending trends in 2026? The biggest commercial lending trends in 2026 are AI-assisted underwriting moving from pilots into daily workflows, a rebound in C&I loan demand, rising rates after the Fed’s September 2026 hike, an $875 billion wave of maturing commercial real estate loans, fast-growing competition and partnership with private credit, and automation aimed at clearing deal backlogs. Lenders that connect origination, servicing, collateral and portfolio data on one platform are best placed to act on all of them.
Commercial lending looks very different at the end of 2026 than it did a year ago. Loan demand from businesses has recovered, rates are rising again, and commercial lending technology, led by AI, has moved from experiment to expectation inside credit teams.
This guide covers the nine commercial lending trends shaping 2026, backed by the latest data from the Federal Reserve, the FDIC and the Mortgage Bankers Association. Each section explains what is changing, why it matters for banks and credit unions, and what to do about it. Each section explains what is changing, why it matters for banks and credit unions, and what to do about it. If you are new to the topic, start with our overview of commercial lending in the US and the commercial lending process.
What are Commercial Lending Trends?
Commercial lending trends are the shifts in how banks, credit unions and nonbank lenders originate, underwrite, price and manage loans to businesses. They are driven by three forces: the economy (rates, demand and credit quality), regulation, and technology. Tracking them helps lenders decide where to grow, where to tighten, and what to automate.
Lending with an eye toward ESG is growing; banks are choosing companies that complement sustainability initiatives. Rising rates of interest are influencing borrowing expenses, which makes companies more wary. Customized loan products and embedded finance solutions are becoming increasingly popular because they provide flexible, industry-specific funding choices for companies of all kinds.
The Commercial Lending Market in 2026: Key Numbers and Benchmarks
The US commercial lending market is growing again in 2026, with healthy credit quality overall but pockets of stress in construction and maturing real estate loans.
Indicator
Latest figure
Source
Fed funds target range
3.75%–4.00% after a 25 bp hike on Sept 16, 2026, the first increase since 2023; prime rate 7.00%
These numbers set the backdrop for the commercial lending trends below, and three things stand out. Demand is back, especially from larger firms. Rates are moving up, not down, which raises refinancing risk. And the fastest-growing part of bank balance sheets is lending to other lenders, which shows how much private credit now shapes the market.
1. AI-assisted underwriting moves from pilot to production
Of all the commercial lending trends this year, AI has moved fastest. It has gone mainstream in 2026, but mostly as an assistant to credit teams rather than a replacement for them. In AI in Lending Market Study, 79% of institutions had AI pilots or AI built into lending workflows by July 2026, up from 34% in late 2025. Faster loan decisions were the top benefit banks wanted, and privacy and cybersecurity risk was the top concern. Community banks are earlier on the curve. A 2026 summary of the CSBS community bank survey found 53% piloting AI or using it in limited functions, and only 11% offering automated loan underwriting today.
The most common uses are financial statement analysis, document extraction, covenant monitoring and credit memo drafting. The San Francisco Fed also found that banks using AI more heavily earned higher returns but carried more problem loans, a reminder that model governance matters.
2. Business lending trends: C&I loan demand rebounds, led by larger firms
C&I loan demand has turned positive in 2026 after a weak 2025. In the Fed’s July 2026 Senior Loan Officer Opinion Survey, banks reported unchanged C&I standards and stronger demand from large and middle-market firms, while small-firm demand was roughly flat. Total bank loans grew 1.8% in Q2 2026, and community bank loans rose 1.6% to $1.9 trillion, according to the FDIC.
What to do: make sure origination can absorb a rising pipeline without adding headcount. Lenders still running deals through email and spreadsheets will feel the strain first. See how commercial loan origination software handles intake, spreading and approvals in one flow.
3. Commercial credit risk trends: rates rise again
The Federal Reserve raised the fed funds rate by 25 basis points to 3.75%–4.00% on September 16, 2026, its first hike since 2023. Most FOMC participants projected one more hike before year-end, according to J.P. Morgan’s review of the September projections. Higher rates squeeze borrowers’ debt service coverage and push some deals out of the credit box. They also make loan pricing and deposit relationships more important.
What to do: stress-test floating-rate borrowers at +50 and +100 bp, reprice renewals deliberately, and watch DSCR trends across the book with loan portfolio management software.
4. The CRE maturity wall: $875 billion comes due
About $875 billion of commercial and multifamily mortgages, 17% of the $5.0 trillion outstanding, is scheduled to mature in 2026, with $652 billion more in 2027, according to the Mortgage Bankers Association. Banks and other depositories hold $396 billion of the 2026 maturities. Among all commercial lending trends, this one carries the most direct credit risk, because many of these loans were written when rates were far lower. Office loans and construction loans carry the most risk; the construction and development noncurrent rate reached 0.99% in Q2 2026, above the all-loan rate. The upside is volume. MBA forecasts commercial mortgage originations rising 27% to about $805.5 billion in 2026 as maturing loans refinance.
What to do: build a maturity calendar 12 to 18 months out, re-underwrite at today’s rates, update collateral values, and decide early between extend, restructure or exit. Tools for asset and collateral management and CRE lending make this work repeatable.
5. Private credit is both competitor and customer
Private credit has become a permanent part of commercial lending, and banks now compete with it and fund it at the same time. The Financial Stability Board’s May 2026 report puts the market roughly on par with the high-yield bond market. For banks, this means lost middle-market deals on one side and a fast-growing, lower-touch lending line on the other. Regulators are watching these exposures closely, which makes this one of the commercial lending trends most likely to carry into 2027.
What to do: win on speed and relationship for deals you want to keep, consider partnerships or fund-finance lines for deals you cannot hold, and monitor concentration to nonbank lenders. Asset-based lending is one area where banks still hold an edge, supported by strong ABL lending software.
Lenders clear deal backlogs by removing manual handoffs, not by hiring more analysts. The biggest delays usually sit in document collection, financial spreading, credit memo writing and approval routing. Banks report sharp gains when they automate these steps. Customers Bank cut commercial loan closing time to seven days from 30 to 60 days in a 2026 pilot, as tracked by Banking News AI. Are automated workflows better than manual processes? For routine tasks, yes: they are faster, more consistent and easier to audit. Credit judgment on complex deals still belongs with experienced underwriters, who should spend their time there instead of on data entry.
The commercial lending digital transformation tools with the fastest payback are usually digital loan intake, automated financial spreading, workflow routing with service-level timers, e-signature, and a borrower portal. Together they remove most of the waiting time in a typical deal.
7. Regulation and RegTech: compliance built into the workflow
Compliance pressure in commercial lending now comes from many directions: model risk rules for AI, third-party risk management, BSA/AML and beneficial ownership checks, and closer supervision of CRE and nonbank exposures. RegTech, or regulatory technology, automates these checks inside the lending workflow, keeping audit trails, flagging exceptions and tracking policy changes. That is cheaper and safer than a separate compliance review at the end.
8. Digital borrower experience and open data become standard
One of the most visible commercial lending trends is on the borrower side: business borrowers now expect the same digital experience they get from consumer apps: online applications, secure document upload, real-time status and e-signatures. APIs and open banking let lenders pull financial and accounting data directly instead of chasing PDFs. This also fuels embedded lending, where credit is offered inside software that businesses already use.
9. New demand from infrastructure, data centers and sustainable finance
Some of the strongest 2026 loan demand comes from data centers, power and grid infrastructure, manufacturing reshoring and energy projects. These deals are large, capital intensive and often syndicated or shared with private credit. Sustainability-linked loans remain part of the mix, with pricing tied to borrower targets such as emissions or energy efficiency. Interest is more selective than in 2022, but the reporting requirements have not gone away.
What to do: build sector expertise for infrastructure and energy credits, and make sure your systems can track project milestones, covenants and sustainability KPIs over the life of the loan.
What these trends mean for Banks and Credit Unions?
The nine commercial lending trends point to one conclusion: commercial lenders need connected data and workflows across the whole loan lifecycle. Rising demand, rate risk, CRE maturities and private credit competition all reward lenders who can decide faster and see risk sooner.
Trend
Pressure it creates
Capability that answers it
AI underwriting
Pressure to decide faster without losing control
Automated spreading and credit memos with human approval
Commercial real estate lending trends are increasingly shaped by changing interest rates, tighter credit standards, evolving property markets, digital transformation, and the growing use of artificial intelligence. Banks, credit unions, and commercial real estate lenders are adopting technology to streamline loan origination, automate underwriting, improve borrower communication, and strengthen portfolio risk management. At the same time, lenders are paying closer attention to property valuations, debt-service coverage, loan-to-value ratios, borrower financials, and changing market conditions. These trends are driving greater demand for commercial lending software, digital lending platforms, AI-powered underwriting, automated workflows, and real-time loan portfolio monitoring.
Key Commercial Real Estate Lending Trends
Digital transformation in CRE lending: Lenders are replacing manual, paper-heavy processes with digital loan origination platforms, electronic document management, automated workflows, and online borrower portals.
AI-powered underwriting: Artificial intelligence and machine learning are increasingly being used to analyze borrower financials, property data, credit information, and other lending factors to support faster and more consistent underwriting decisions.
Automated loan origination: Commercial lending technology can automate tasks such as application intake, document collection, credit analysis, approval workflows, and loan closing, helping reduce processing time and manual work.
Stronger CRE risk management: Lenders are placing greater emphasis on monitoring property values, borrower financial health, debt-service coverage ratios, loan-to-value ratios, and other indicators throughout the loan lifecycle.
Real-time portfolio monitoring: Modern loan portfolio management software enables lenders to monitor commercial real estate loans, identify potential risks, track financial performance, and manage upcoming reviews or reporting requirements.
Automated covenant and exception tracking: Lenders are using technology to monitor covenant requirements, missing documents, policy exceptions, and other conditions that may require attention or follow-up.
Improved borrower experience: Digital borrower portals allow commercial real estate borrowers to submit documents, check application status, communicate with lenders, and complete lending tasks online, creating a more transparent lending experience.
Data-driven lending decisions: Lenders are bringing together borrower, financial, property, and portfolio data to improve credit analysis and support more informed commercial real estate lending decisions.
Cloud-based commercial lending platforms: Cloud technology is helping banks and credit unions centralize lending data, connect lending workflows, and provide easier access to information across credit, operations, and portfolio management teams.
Focus on loan portfolio quality: Beyond originating new loans, lenders are increasingly focused on managing existing CRE portfolios, identifying emerging risks, monitoring loan performance, and maintaining accurate borrower and property information.
Why Commercial Real Estate Lending Trends Matter?
These commercial real estate lending trends are changing how lenders originate, underwrite, manage, and monitor CRE loans. Technology can help reduce manual processes while giving lenders greater visibility into borrower and portfolio information. For banks and credit unions, adopting modern commercial lending software can support faster workflows, better exception management, stronger risk monitoring, and a more efficient borrower experience throughout the commercial real estate loan lifecycle.
Conclusion: Acting on commercial lending trends in 2026 and beyond
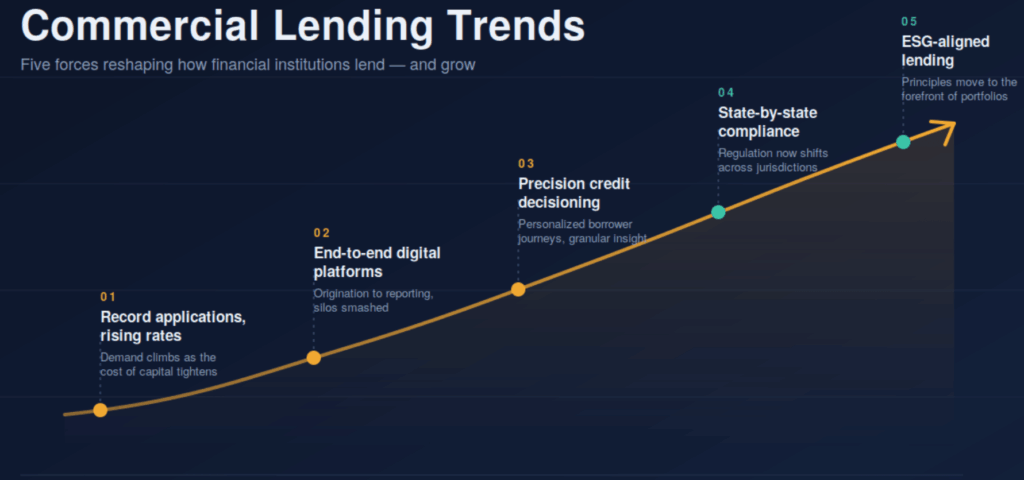
The commercial lending trends of 2026 — record-high business applications, rising interest rates, evolving compliance demands, and the push toward ESG-aligned lending — are not challenges to wait out; they are signals to act on. New business applications are at a record high, but so are US interest rates. Though it seems to be happening piecemeal, technological transformation is already underway. Borrowers want personalized and streamlined experiences, but their satisfaction requires precise credit decision-making models. Compliance requirements change from state to state—unheard of until recently. Strengthening satisfactory lending and ESG principles is rapidly coming to the forefront but is also subject to serious risks. Financial institutions have to capitalize on current trends or risk becoming obsolete.
While our platform provides an end-to-end solution, it is not a universally applicable product. From loan origination and underwriting to reporting and precise analytics, our automated solution propels revenue generation. By smashing silos with a digitized lending platform, our services enable our customers to maximize growth and operational efficiency. Our granular customer insights allow our clients to scrutinize every prospect thoroughly, making informed commercial lending decisions.
What are the top commercial lending trends in 2026?
The top trends are AI-assisted underwriting, a rebound in C&I loan demand, rising interest rates, $875 billion in maturing commercial real estate loans, growing private credit competition, automation to clear deal backlogs, embedded compliance, digital borrower experiences, and new demand from infrastructure and data center projects.
Is commercial lending volume increasing in 2026?
Yes. US bank loans grew $243.5 billion (1.8%) in Q2 2026 to $13.9 trillion, according to the FDIC. The Fed’s July 2026 loan officer survey showed stronger C&I demand from large and middle-market firms, while small-business demand turned slightly positive after a weak 2025.
How do lenders clear deal backlogs?
Lenders clear deal backlogs by automating the slowest manual handoffs: document collection, financial spreading, credit memo drafting and approval routing. A single workflow platform lets analysts see every deal’s status, removes re-keying between systems and frees underwriters to focus on credit decisions rather than data entry.
Are automated commercial lending workflows better than manual processes?
For routine work, yes. Automated workflows are faster, more consistent and easier to audit than email and spreadsheets. They are best used to handle data gathering, checks and routing, while experienced underwriters keep responsibility for judgment calls on complex credits.
How is AI changing commercial lending?
AI speeds up document review, financial spreading, covenant monitoring and credit memo drafting. Abrigo’s 2026 study found 79% of institutions had AI pilots or AI built into lending workflows by July 2026. Most lenders keep a human in the final credit decision and apply model risk governance.
What is RegTech in commercial lending?
RegTech, or regulatory technology, uses software to automate compliance tasks such as KYC, AML and OFAC screening, exception tracking, audit trails and regulatory reporting. Built into the lending workflow, it reduces manual checks and makes exams easier to support.
What are sustainability-linked loans?
Sustainability-linked loans are commercial loans whose pricing depends on the borrower meeting agreed sustainability targets, such as cutting emissions. Unlike green loans, the proceeds can usually be used for general corporate purposes.
What technology do commercial lenders need in 2026?
Most lenders need digital origination, automated spreading and credit analysis, a borrower portal, collateral and covenant tracking, embedded compliance checks, and real-time portfolio monitoring, ideally on one connected commercial lending platform.
Are there any recent trends in commercial capital financing?
Yes. In 2026, the main shifts in commercial capital financing are stronger bank C&I demand, higher borrowing costs after the Fed’s September rate hike, heavy CRE refinancing, and a bigger role for private credit and asset-based lending. Borrowers are also getting faster, more digital loan processes.
What commercial lending benchmarks should lenders track?
Key commercial lending benchmarks include loan growth (US bank loans grew 1.8% in Q2 2026), the noncurrent loan rate (0.93% industry-wide), net charge-offs, time from application to decision, time to close, and pull-through rate. Comparing your own figures to FDIC and Fed data shows where you lag the market.