Commercial Lending in the USA: Complete Guide for Commercial Lenders in 2026
Commercial lending in the US refers to how banks and financial institutions provide loans to businesses for operations, expansion, real estate, and working capital. The process includes application, underwriting, approval, funding, and ongoing portfolio management.
For borrowers, commercial lending is about getting the right amount of capital at terms that fit the business. For banks and other lenders, however, the process is much broader. A commercial loan has to be evaluated, structured, approved, documented, funded, serviced, monitored, and managed throughout its lifecycle.
According to the Mortgage Bankers Association (MBA), commercial and multifamily borrowing reached approximately $706 billion in 2025, representing a 40% increase over 2024. Multifamily lending alone accounted for $413 billion, while banks and depository institutions continued to be the largest providers of commercial credit. These numbers highlight continued demand for business financing despite a complex economic environment. The U.S. commercial lending market remains a major economic driver, with commercial real estate borrowing and lending reaching $706 billion in 2025, a 40% increase from 2024. Multifamily loans accounted for $413 billion, while depository institutions remained the leading source of commercial credit.
Commercial lending is a debt instrument advanced to support business activity and growth – and it’s at least as old as the age of agriculture. Commercial lending has been crucial in fuelling economic growth in the US and continues to power businesses with various credit instruments that allow them to purchase equipment, commercial real estate, pay for startup costs, and more. In effect, the commercial loan is the lifeblood of businesses large and small.
This guide explains how commercial lending works in the USA, the different types of commercial lenders and loans, how banks evaluate commercial borrowers, what happens after a loan is funded, and how technology is changing commercial lending operations.
– Commercial lending is credit extended to a business for business purposes, spanning everything from a revolving working-capital line to a multi-year commercial real estate mortgage.
– US commercial banks held roughly $2.89 trillion in commercial and industrial (C&I) loans as of June 2026, according to the Federal Reserve’s H.8 release.
– Commercial real estate is measured separately. The Mortgage Bankers Association estimated $706 billion of CRE mortgage borrowing and lending in 2025, a 40% increase over $505 billion in 2024.
– Four lender categories dominate — commercial banks, community banks, credit unions, and nonbank specialty lenders — each under a different regulator with a different rulebook.
– The lender’s work does not end at funding. Servicing, covenant testing, collateral tracking, risk rating and portfolio management run for the life of the loan, and that is where most of the operational cost sits.
What is Commercial Lending in the US?
Commercial lending is the process of providing credit to businesses and other commercial borrowers for business-related purposes. A commercial loan can be secured or unsecured and may be structured as a term loan, revolving line of credit, working capital facility, equipment loan, commercial real estate loan, or another type of business financing. Commercial lending in the US is the process of providing loans to businesses to fund operations, expansion, or investments. Banks, credit unions, and financial institutions typically offer these loans, which can be secured or unsecured.
Commercial loans typically involve larger loan amounts, more complex underwriting processes, customized repayment structures, and ongoing portfolio monitoring. Because commercial loans often represent significant financial exposure, lenders rely on detailed credit analysis, risk assessment, covenant monitoring, and regulatory compliance throughout the loan lifecycle.
Modern commercial lending combines traditional relationship banking with advanced technologies such as AI-powered underwriting, workflow automation, predictive analytics, digital borrower portals, and real-time portfolio monitoring.
The FDIC describes commercial and industrial lending as secured or unsecured credit provided to business enterprises for commercial and industrial purposes. This can include working-capital advances, term loans, and certain loans to individuals for business purposes. The OCC similarly explains that companies use commercial credit to meet financial obligations, fund daily operations and new opportunities, purchase equipment, and address unexpected expenses.
In simple terms, commercial lending connects businesses that need capital with lenders that evaluate and manage the risk associated with providing that capital. But commercial lending does not end when the borrower receives the money. For the lender, the loan becomes part of a broader credit relationship and, ultimately, part of the institution’s commercial loan portfolio.
Platforms like Finanta’s Commercial Lending Solution enable financial institutions to digitize every stage of the lending lifecycle—from loan origination and credit decisioning to document management, collateral tracking, covenant monitoring, servicing, and portfolio management—helping lenders improve efficiency while delivering a better borrower experience.
It has a few key characteristics:
– Such loans require the business to post collateral such as cash, real-estate holdings, plant and equipment, or any asset that the lender can repossess if the business defaults.
– The business must also be deemed creditworthy: it must usually submit documents demonstrating stable cash flows to establish that it can repay the lender based on the loan terms.
– Such loans also have more flexible credit structures than personal loans – in fact, some businesses can qualify for unsecured loans so long as the applicant signs a personal guarantee to pay it back if the business fails. Loans can even be unsecured by collateral, provided the applicant signs a personal guarantee to pay it back in case the business fails.
Why Commercial Lending Matters in the USA?
Commercial lending is a key driver of economic growth in the United States. Access to capital helps companies to innovate, enter new markets, buy equipment, engage employees, build commercial spaces, and increase efficiency. For financial institutions, commercial lending is an essential source of revenue and long-term customer connections. However, due to increased competition, rising borrower demands, and regulatory complexity, lenders must modernize conventional lending processes.
Digital transformation is now recognized as a strategic focus for institutions seeking to minimize manual procedures, enhance credit decisioning, streamline approvals, and improve risk management. Modern commercial lending systems allow lenders to optimize operations while remaining compliant and providing excellent client experiences.
Commercial lending in the US has closely followed economic cycles. After the Revolutionary War, early banks lent to entrepreneurs, helping rebuild the economy. Post-Civil War commercial institutions funded infrastructure and industrial growth, sparking a second industrial revolution. The Great Depression marked the lowest point for commercial lending in the US, with loan volumes plummeting nearly 60% as the banking system collapsed. Recovery came with reforms like the Glass-Steagall Act, and the post-World War II boom, which revived lending. However, the Great Recession of 2008 saw a 16% drop in loan volumes, echoing past downturns. The most transformative change came with the digital age during the ’80s when online lending platforms disrupted traditional banking , and we will discuss both traditional and modern players in the industry in the following sections.
There is no single number, because “commercial lending” spans two datasets measured in fundamentally different ways. Quoting one for the other is the most common error in this topic.
Measure
Value
Period
Source
C&I loans outstanding, all commercial banks
~$2.89 trillion
June 2026
Federal Reserve H.8 (BUSLOANS, seasonally adjusted)
CRE mortgage borrowing and lending, originations
$706 billion
Full-year 2025
MBA annual report, 28 April 2026
Prior-year CRE originations
$505 billion
Full-year 2024
MBA, same report
Two years prior
$429 billion
Full-year 2023
MBA, same report
Multifamily share of CRE lending
$413 billion
Full-year 2025
MBA, same report
Forecast total commercial mortgage originations
$805.5 billion
2026 forecast
MBA CREF Forecast, 9 February 2026
Forecast multifamily originations
$399.2 billion
2026 forecast
MBA CREF Forecast, 9 February 2026
Two notes on reading these figures correctly:
C&I balances are a stock; CRE origination figures are a flow. The $2.89 trillion is what banks hold on balance sheet at a point in time. The $706 billion is what was originated across a full year. They are not comparable and should never be added together.
MBA publishes two different multifamily numbers. Its annual CREF summation estimates $413 billion of total multifamily lending in 2025. Its separate annual multifamily lending report counts $381.8 billion originated by 2,530 lenders, a 32% increase over 2024. The methodologies differ — the summation estimates activity from smaller depositories that the survey does not directly capture. Cite whichever fits the question and name the report.
What both datasets show is the same directional story: after a constrained 2023 and 2024, origination activity recovered sharply through 2025 as rate expectations stabilised and pricing became clearer, and C&I balances came off a long post-2023 plateau.
How Commercial Lending Work in the US?
The exact process varies by lender and loan type, but most commercial lending follows a similar lifecycle:
#
Stage
What happens
Who owns it
1
Application
Borrower submits the request, purpose, financials, ownership detail and collateral
Relationship manager
2
Financial analysis
Spreading of statements, tax returns, AR/AP aging, projections
Stages 1 through 8 decide whether to lend and on what terms. Stages 9 and 10 are where most of the ongoing operational cost actually sits — and where spreadsheet-based processes break down first as a portfolio grows.
Across institutions, the eligibility picture is consistent: a record of consistent debt service and manageable existing leverage, demonstrable and repeatable cash flow, collateral of sufficient quality and value, credible management, and an industry outlook that supports the repayment assumption. Collateral is rarely just a threshold requirement — its quality directly shapes pricing, advance rates and structure.
Where applications commonly fail
Businesses struggle most when the economy tightens and they have to prove stability against a weaker recent trend. Rising rates raise the debt service burden and can push a marginal DSCR below covenant. Younger businesses with limited operating history have no track record to underwrite against. And borrowers frequently underestimate the documentation burden: incomplete or inconsistent financial information is one of the most common causes of delay and decline.
Commercial Loan Process
Commercial lending in the US involves several key steps:
– Credit Evaluation: A strong credit history and a steady revenue stream – if the business is already in operation – will help the lender assess the customer’s capacity to repay.
– Collateral Assessment: Collateral is not only one of the main requirements for a loan, but the quality of collateral can help the customer get loans at much better terms.
– Loan Underwriting: Lenders judge the risks involved in fixing the loan amount, the interest rate, and the repayment terms.
– Approval and Disbursement: Once approved, the loan is disbursed, and the business begins repayment under the agreed-upon terms.
Key Eligibility Criteria
All lenders look for much the same things when deciding whether to give out a loan. A history of regular payments and low debt increases your chances of approval. A steady flow of revenue means the business is in good financial health. Collateral is not only a minimum requirement, but in most cases, its value directly impacts loan terms.
Common Challenges in Securing Commercial Loans
Businesses usually face challenges in securing loans when the economy is in a slump – this puts them under pressure to demonstrate their financial stability. Rising interest rates just make borrowing more costly for everyone, affecting businesses as well. New businesses with a short credit history can find it hard to show they are creditworthy and may be scrutinized further or simply rejected. And regulations, both federal and local, have now become a minefield for small businesses to navigate, and it is worth noting that commercial lending wasn’t even regulated at any level until recently.
The Corporate Finance Institute states that commercial loans have far more complicated structures than other loan types, and this complexity extends to the screening of applicants as well, with credit analysis ultimately deciding whether a business secures a loan or not.
Who Provides Commercial Loans in the USA?
Commercial lending is not limited to large national banks. Four categories of provider compete, each supervised differently.
Lender type
Primary regulator
Typically strongest at
Notable constraint
Commercial banks (national)
OCC
Large C&I facilities, syndications, treasury and cash management
Legal lending limits, concentration guidance
Community banks
FDIC / state / OCC
Local CRE, small and middle-market relationships
Capital and concentration limits
Credit unions
NCUA
Member business loans, professional and agricultural credit
Member business lending rules; commercial expertise requirements
Nonbank and specialty lenders
State licensing; varies
Asset-based lending, private credit, industry niches
Cost of capital; no deposit funding
Commercial Banks
Commercial banks are among the most established providers of business credit in the United States.
Depending on their size and business model, banks may provide:
– Commercial and industrial loans
– Working capital lines
– Equipment financing
– Commercial real estate loans
– Construction financing
– Acquisition financing
– Term loans
– Treasury and cash-management services
– Other business credit facilities
Large banks often have specialized commercial banking teams, credit officers, relationship managers, industry groups, and centralized underwriting functions. The OCC maintains extensive commercial-credit guidance covering areas such as underwriting, risk rating, commercial real estate, concentrations and portfolio management, problem loans, lending limits, and other commercial-credit risks.
Community Banks
Community banks are another important source of commercial financing, particularly for small and middle-market businesses. One of their potential advantages is their knowledge of local markets and business relationships. A community bank may understand the economic conditions, industries, property markets, and business owners in its geographic area particularly well.
Community banks may offer:
– Business lines of credit
– Commercial real estate financing
– Equipment loans
– Working capital facilities
– Term loans
– Construction loans
– Relationship-based commercial banking
Technology is increasingly relevant to community banks because they need to balance the relationship-oriented nature of their lending model with the operational demands of managing a growing commercial portfolio. In July 2026, the OCC announced changes to the Community Bank Leverage Ratio framework and estimated that the changes could provide additional capacity for community banks to support lending.
Credit Unions
Credit unions can also participate in commercial lending, although their regulatory framework and lending requirements differ from those applicable to banks.
The NCUA defines a commercial loan as a loan, line of credit, or letter of credit made for commercial, industrial, agricultural, or professional purposes. Its guidance includes commercial real estate loans, term business loans, working-capital lines, and other forms of commercial financing. The NCUA also points out that commercial lending can be more complex and involve different risks than consumer lending. Credit unions engaged in commercial lending need appropriate expertise, resources, policies, and ongoing risk-management practices.
Specialized and Nonbank Commercial Lenders
Businesses may also obtain financing from specialized commercial lenders, finance companies, private-credit providers, and other nonbank institutions. These lenders may focus on particular industries, asset classes, loan sizes, borrower profiles, or financing structures.
The right lender therefore depends on several factors, including the borrower’s financial position, financing purpose, collateral, industry, required loan structure, and the lender’s risk appetite.
Types of Commercial Loans in the USA
Commercial lending includes a broad range of financing products. The right structure depends on what the borrower needs the money for and how the lender expects the debt to be repaid.
Loan type
What it funds
Primary repayment source
Typical collateral
C&I term loan
Equipment, expansion, acquisitions
Operating cash flow
Business assets, blanket lien
Working capital line of credit
Payroll, inventory, receivables, seasonality
Conversion of receivables and inventory
Borrowing base of AR and inventory
Commercial real estate mortgage
Acquisition or refinance of income-producing property
Property net operating income
The property, assignment of rents
Construction and development
Ground-up build or major redevelopment
Take-out financing or sale proceeds
The project, completion guaranty
Equipment finance
Machinery, vehicles, technology
Operating cash flow
The financed equipment
SBA 7(a)
Broad general business purposes
Operating cash flow
Varies; SBA guaranty reduces lender exposure
SBA 504
Owner-occupied real estate and heavy equipment
Operating cash flow
Real estate or equipment; CDC participation
Commercial and Industrial Loans
C&I lending funds operating activity and investment — working capital, inventory, equipment, expansion, business acquisitions and operating expenses. The FDIC identifies working-capital advances and term loans as the two canonical C&I forms. Repayment comes from the borrower’s operating cash flow, which is why debt service coverage is the central underwriting metric.
Common uses include:
– Working capital
– Inventory
– Equipment
– Expansion
– Business acquisitions
– Operating expenses
– Other business investments
The FDIC identifies working-capital advances and term loans as examples of commercial and industrial lending.
Working Capital Lines of Credit
A working capital line gives a business access to financing as needed. Instead of borrowing the full amount at once, the borrower can draw funds according to the terms of the facility and repay them as cash becomes available.
Businesses may use these facilities to manage:
– Payroll
– Inventory
– Accounts receivable
– Seasonal cash-flow needs
– Operating expenses
The NCUA identifies seasonal and revolving lines of credit among common forms of commercial lending.
Commercial Real Estate Loans
Commercial real estate, or CRE lending finances the acquisition, development, construction, refinancing or improvement of commercial property — office, retail, industrial, multifamily, hospitality, mixed-use and owner-occupied.
CRE underwriting is unusually sensitive to property cash flow, occupancy, market conditions, sponsor strength and appraised value. Because repayment depends on the asset rather than an operating business, CRE concentration is a standing supervisory concern.
Examples can include:
– Office properties
– Retail properties
– Industrial properties
– Multifamily properties
– Hotels
– Mixed-use properties
– Owner-occupied commercial real estate
The FDIC defines CRE lending to include acquisition, development, and construction financing as well as financing of income-producing real estate. CRE loans can require particularly careful underwriting because repayment may depend on property cash flow, occupancy, market conditions, borrower strength, and collateral value.
Equipment Financing
Equipment financing allows businesses to acquire machinery, vehicles, technology, production equipment, and other business assets without necessarily funding the entire purchase from operating cash. The financed equipment may also serve as collateral, depending on the loan structure.
Construction and Development Loans
Construction and development loans finance the development or construction of commercial properties and other projects.
These loans can carry additional risks because repayment may depend on factors such as:
Project completion
Construction costs
Leasing
Property sales
Market conditions
Final property value
Developer performance
SBA-Backed Loans
The Small Business Administration’s 7(a), 504 and Microloan programs allow participating lenders to extend credit to small businesses that would not fit conventional structures, with a federal guaranty absorbing part of the loss exposure. SBA financing is often the difference between a decline and an approval for younger businesses or thinner collateral positions.
Commercial Lending vs. Consumer Lending
Commercial lending and consumer lending have different purposes and often require different underwriting and servicing processes.
Dimension
Commercial lending
Consumer lending
Purpose
Business operations, investment, acquisition
Personal consumption
Primary credit basis
Business cash flow and debt-service capacity
Personal income and credit score
Borrower structure
Often multiple entities, guarantors, subsidiaries, holding companies
Usually a single individual or household
Underwriting
Bespoke, analyst-led, document-intensive
Largely automated and standardised
Typical collateral
Commercial real estate, equipment, inventory, receivables
A commercial borrower may operate through several entities, with an operating company, a property-holding company, personal guarantors, and more than one source of repayment. That structural complexity is why commercial credit administration is so much more information-intensive than consumer servicing.
The Commercial Lending Process in the USA
1. Application
The process typically starts when a business submits an application describing the financing request and the purpose of the loan.
The lender may collect information about:
-The business
– Ownership
– Management
– Financial performance
– Existing debt
– Collateral
– Financing purpose
– Projected cash flow
2. Financial Analysis
Lenders generally review financial information to understand the borrower’s ability to generate sufficient cash flow to support its obligations.
Depending on the borrower and loan, this can include:
– Balance sheets
– Income statements
– Cash-flow statements
– Tax returns
– Accounts receivable
– Accounts payable
– Bank statements
– Existing debt
– Financial projections
3. Credit Underwriting
Underwriting is where the lender evaluates whether the proposed credit fits its risk appetite and lending policies.
The analysis may consider:
– Historical financial performance
– Cash flow
– Debt-service capacity
– Leverage
– Liquidity
– Management experience
– Industry conditions
– Existing obligations
– Repayment sources
– Collateral
– Guarantees
The OCC identifies underwriting as one of the core areas within its commercial-credit supervisory framework. OCC: Commercial Credit
4. Collateral Evaluation
When a loan is secured, the lender may evaluate the assets supporting the credit.
Collateral may include:
– Commercial real estate
– Equipment
– Inventory
– Accounts receivable
– Securities
– Vehicles
– Other business assets
Depending on the collateral, the lender may need appraisals, valuations, lien searches, insurance documentation, UCC filings, and other supporting information.
5. Risk Rating
Commercial lenders commonly use risk-rating systems to classify the credit quality of loans or borrowers.
Risk ratings help lenders identify changes in credit quality and understand how individual loans affect the broader portfolio.
The OCC specifically includes risk rating and concentrations/portfolio management among its commercial-credit resources. OCC: Commercial Credit
6. Credit Approval
Once underwriting is complete, the loan moves through the lender’s approval process.
Depending on the institution and loan size, approval may involve:
– Relationship managers
– Credit analysts
– Underwriters
– Credit officers
– Loan committees
– Senior management
7. Documentation and Closing
After approval, the lender prepares and completes the required loan and collateral documentation.
This can include:
– Loan agreements
– Promissory notes
– Security agreements
– Guarantees
– Mortgage documents
– Insurance
– Collateral documentation
– Closing conditions
8. Funding
Once the closing requirements have been satisfied, the lender funds the loan according to the approved structure.
But the work does not stop there.
9. Servicing and Monitoring
After funding, the lender may need to monitor:
– Payments
– Financial statements
– Covenants
– Insurance
– Collateral
– Borrower requests
– Documentation
– Risk ratings
– Exceptions
10. Portfolio Management
Individual loans are ultimately part of a larger commercial loan portfolio.
That means lenders also need to understand aggregate exposure and concentration risk.
Commercial Loan Portfolio Management
Commercial loan portfolio management is the ongoing monitoring of credit quality, exposure and performance across a lender’s entire commercial book, rather than loan by loan.
It matters because a portfolio can deteriorate while every individual loan still looks acceptable. A hundred sound loans against the same property type in the same metro is a concentration, not a diversified book. The OCC identifies concentrations and portfolio management as a distinct area of commercial credit supervision for exactly this reason.’
Core activities include:
– Risk-rating distribution and migration analysis
– Exposure monitoring by borrower, relationship and related interests
– Concentration analysis by industry, geography, property type and collateral type
– Covenant and collateral exception tracking in aggregate
– Financial statement tickler management
– Delinquency and non-accrual trending
– Stress testing against rate, vacancy and cash-flow scenarios
– Portfolio segmentation and vintage analysis
The practical test is simple: can the lending team answer “what is our total exposure to this industry, at what average risk rating, with what exception rate?” in minutes rather than days.
The Role of Collateral in Commercial Lending in the US
Collateral is a secondary repayment source, not a substitute for cash flow. Its value to the lender depends entirely on the quality of the information held about it.
A lender needs current, retrievable data on collateral type and description, current value and appraisal date, loan-to-value, insurance coverage and expiry, lien position, UCC filing and continuation dates, perfection status, borrowing-base eligibility, and open exceptions. Across a few hundred loans this is a spreadsheet problem. Across a few thousand it becomes a systems problem — and the failure mode is discovering a lapsed insurance policy or an expired UCC filing at the moment of default, when it is too late to fix.
The NCUA’s commercial lending guidance treats collateral as a specific area of loan administration and risk management, not an afterthought to underwriting.
Glossary
– Covenant — a contractual condition the borrower must maintain (financial, such as a minimum DSCR) or perform (non-financial, such as delivering audited statements within 120 days).
– Risk rating — an internal grade reflecting probability of default and, on dual-rating systems, loss given default.
– Borrowing base — the formula-driven availability cap on a revolving line, based on eligible receivables and inventory.
– Perfection — the steps, typically a UCC-1 filing, that make a security interest enforceable against third parties.
– DSCR — debt service coverage ratio: cash available for debt service divided by required debt service.
– LTV — loan amount divided by appraised collateral value.
The Importance of Credit Analysis in Commercial Lending
Modern credit analysis essentially helps lenders decide whether an applicant gets a loan or not – it is the linchpin of commercial lending and is computed using several metrics:
Credit scoring: The credit score essentially tells the lender just how risky it is to lend to a business. Models like FICO and VantageScore tell the lender the chance of the borrower defaulting, mainly by analyzing their financial conduct, and this is one of how the lender decides the interest rate.
Financial ratios: While the credit score looks into the borrowers’ financial history, financial ratios help scrutinize the company’s financial health. Ratios such as a company’s debt-to-equity ratio, interest coverage ratio, and current ratio help lenders determine whether the borrower will be able to repay.
The Role of Technology: AI and machine-learning models have taken credit analysis to the next level, allowing lenders to parse vast amounts of data and make faster credit assessments. Such technologies also reduce human error and bias in evaluating collateral and the borrower’s capacity to repay.
Credit analysis is the foundation on which a lender issues a loan – not only does it determine interest rates and repayment periods, but also protects both the borrower and the lender and helps stabilize the economy – from the earliest periods in free America’s history, sound lending practices have directly led to economic prosperity.
What Should Banks Look for in Commercial Lending Software?
There is no single commercial lending platform that is automatically the right choice for every bank, community bank, credit union, or commercial lender.cThe best fit depends on the institution’s lending model, portfolio size, existing technology, operational processes, risk requirements, and budget. When evaluating commercial lending software, financial institutions should consider several areas.
– Loan Origination: Can the platform support applications, underwriting, approvals, documentation, and closing?
– Portfolio Management: Can lenders monitor individual loans and understand the performance of the broader portfolio?
– Collateral Management: Can the system track collateral, valuations, insurance, liens, and related exceptions?
– Covenant Management: Can the lender monitor financial and non-financial covenants and identify exceptions?
– Loan Servicing: Does the platform support post-closing administration and ongoing loan management?
– Borrower Portal: Can borrowers securely submit documents, communicate with lenders, and access relevant information?
– Reporting and Analytics: Can lending teams generate useful portfolio reports and analyze exposure and risk?
– Workflow Automation: Can repetitive manual tasks be automated while preserving approvals, controls, and auditability?
– Integration: Can the technology integrate with the institution’s core banking system and other relevant applications?
– Scalability: Can the system support the institution as its commercial loan portfolio grows?
Commercial Lending Trends in the USA
The U.S. commercial lending environment continues to evolve.
– CRE origination volumes are recovering. MBA’s February 2026 CREF forecast projects total commercial mortgage originations rising to $805.5 billion in 2026, with multifamily at $399.2 billion — driven by stabilising rate expectations, growing confidence that property values have found a floor, and a continuing refinancing pipeline from maturing loans.
– C&I lending has reaccelerated after a prolonged plateau, based on Federal Reserve H.8 balances through mid-2026.
– Portfolio-level risk visibility is the dominant technology ask. Lenders increasingly need concentration views across industry, geography, property type and collateral — not just loan-level review.
– Digital borrower experience is now table stakes in middle-market relationships rather than a differentiator. Businesses expect secure document exchange, status visibility and structured communication.
– AI adoption is concentrated in document work — extraction, spreading, and exception surfacing — where accuracy is directly verifiable. Applications touching credit decisioning carry explainability and fair-lending obligations that materially constrain deployment.
– Regulatory attention on CRE concentration persists, and lenders should expect continued examiner focus on concentration limits, stress testing and the currency of collateral information.
– Track conditions rather than guessing at them. The Federal Reserve’s Senior Loan Officer Opinion Survey (SLOOS) is the standard quarterly read on changes in bank lending standards and loan demand across C&I and CRE categories.
Current Commercial Lending Data and Regulatory Resources
Financial institutions researching the U.S. commercial lending market should use primary regulatory and government sources whenever possible.
– Federal Reserve — Senior Loan Officer Opinion Survey: The Federal Reserve’s SLOOS provides information on changes in lending standards and demand for loans across U.S. banks.
– OCC — Commercial Credit: The Office of the Comptroller of the Currency provides commercial-credit guidance covering underwriting, risk ratings, portfolio management, concentrations, commercial real estate, problem loans, and other areas.
– FDIC — Commercial & Industrial Lending: The FDIC provides information on C&I lending, including working capital advances, term loans, credit administration, and relevant supervisory resources.
– FDIC — Commercial Real Estate Lending: This resource covers acquisition, development and construction financing and income-producing real estate lending.
– NCUA — Commercial and Member Business Loans: Credit unions can use NCUA resources to understand commercial lending definitions, loan types, collateral, risk ratings, administration, and regulatory requirements.
– SBA — Lenders: The SBA provides information about its lending programs and participating lenders.
Commercial Lending Challenges in the USA for Banks and Lenders
Despite improvements in technology, commercial lenders continue to face several operational challenges.
– Manual Data Entry: Information may have to be entered multiple times across applications, spreadsheets, loan systems, and other tools.
– Disconnected Systems: Loan origination, servicing, collateral, document management, and portfolio management may exist in separate systems.
– Collateral Tracking: Keeping collateral values, insurance, appraisals, lien information, and documentation current can be difficult as portfolios grow.
– Covenant Monitoring: Financial and non-financial covenant requirements can be difficult to monitor consistently when processes depend heavily on spreadsheets and manual reminders.
– Exception Management: Missing financial statements, expired insurance, outdated appraisals, documentation gaps, and covenant exceptions can be difficult to track when information is spread across multiple systems.
– Portfolio Visibility: A lender can understand individual loans reasonably well while still lacking a clear view of aggregate exposure across the portfolio.
Technology should support the lender’s policies and credit processes rather than replace professional judgment.
The Future of Commercial Lending in the US
Growth and Technology Adoption:
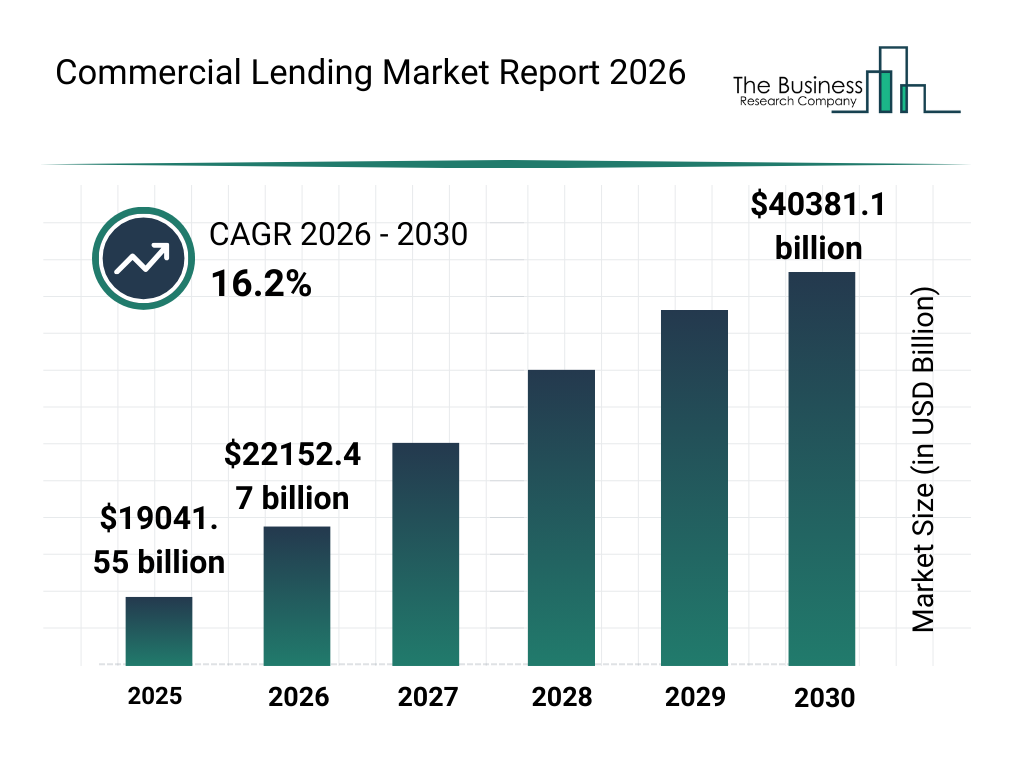
Commercial lending is poised to grow even as it is coming under stricter scrutiny. Experts predict it will grow at an annual rate of 13% over the next decade as interest rates across the world stabilize. In 2023, North America held the lion’s share – about 36% – of this market and will grow alongside the rest of the world, supported by growing demand as businesses return to the office. Commercial loan volumes could see a steady increase thanks to these factors.
Predictive analytics will soon speed up risk assessment, giving borrowers quicker access to capital. Additionally, the adoption of fintech solutions such as Finanta will streamline loan origination and underwriting processes , reducing operational costs and improving customer experience.
Potential Changes in the Regulatory Environment:
Recent regulations at both the federal and local levels do not fall under a unified framework – and if that wasn’t complicated enough, new regulations are expected to tighten lending practices in commercial real estate because of evolving risks in this market.
Players in this space don’t just have to prepare for tighter regulations, but new regulations that promote sustainable businesses or green lending – and this comes with its challenges. Lenders cannot just cut out ‘brown’ businesses and shift to the green lending space, as it comes with its risks.
There is only one constant in commercial lending in the US: the need for advanced technology. As discussed above, America has historically thrived when businesses and entrepreneurs have had ready access to funding, and if regulations make technology adoption necessary to fuel business ambitions, then an end-to-end commercial lending platform is a necessity.
Conclusion
Commercial lending in the USA is a broad and complex part of the financial services industry. Commercial banks, community banks, credit unions, and specialized lenders all play different roles in providing businesses with access to capital. For borrowers, the focus is usually on obtaining financing that fits their business and repayment capacity.
For lenders, the responsibility continues well beyond loan approval. They need to manage underwriting, documentation, servicing, collateral, covenants, financial information, risk ratings, exceptions, and portfolio-level exposure throughout the life of the relationship. That is why commercial lending technology is becoming an increasingly important part of modern lending operations.
The right technology can help connect origination, servicing, portfolio management, collateral, borrower communication, and reporting. But technology should be selected based on the institution’s actual requirements rather than the assumption that one platform is universally the best. For banks, community banks, credit unions, and other commercial lenders, the long-term objective is straightforward: build a commercial lending operation that gives lending teams better information, more efficient workflows, stronger portfolio visibility, and a better experience for borrowers.
Subscribe to our blog for insights on how Finanta’s digital lending platform can streamline the commercial lending process, slashing through the paperwork, the red tape, and regulatory compliance, ensuring that both lenders and businesses thrive.
Commercial lending is the process of providing loans to businesses for working capital, expansion, equipment purchases, commercial real estate, acquisitions, and other business needs. Commercial loans are offered by banks, credit unions, and commercial finance companies based on the borrower’s financial health, repayment capacity, collateral, and creditworthiness.
What are the main types of commercial loans?
Common commercial loan types include term loans, business lines of credit, commercial real estate loans, SBA loans, equipment financing, construction loans, bridge loans, and asset-based lending.
What is commercial lending software?
Commercial lending software is a technology platform that automates the commercial loan lifecycle, including origination, underwriting, document management, approvals, servicing, portfolio management, and compliance.
What documents are required for a commercial loan?
Typical documents include financial statements, tax returns, bank statements, business plans, cash flow reports, balance sheets, profit and loss statements, legal formation documents, and collateral information.
What is the difference between commercial lending and business lending?
Business lending is a broad category that includes loans for businesses of all sizes. Commercial lending generally refers to more complex financing solutions involving larger loan amounts, detailed underwriting, collateral evaluation, and customized loan structures.
what are commercial lending workflows and how do banks typically structure them?
Commercial lending workflows are the processes banks use to manage a loan from application and underwriting through approval, closing, servicing, and ongoing portfolio monitoring. Banks typically structure these workflows into stages such as borrower intake, document collection, credit analysis, risk assessment, approval, loan documentation, closing, and post-closing monitoring. Modern banks increasingly use workflow automation and commercial lending software to reduce manual tasks, improve collaboration, and maintain consistent credit processes.
What are the main types of commercial lending in the USA?
The main types of commercial lending in the U.S. include commercial and industrial (C&I) loans, working capital and revolving lines of credit, term loans, asset-based lending, commercial real estate loans, equipment financing, and SBA-backed loans. Businesses use these financing options for purposes such as working capital, expansion, equipment purchases, acquisitions, inventory, and real estate. The right option depends on the borrower’s financing needs, cash flow, collateral, and repayment capacity.
What are the steps involved in the commercial lending process?
The commercial lending process typically includes loan application, borrower and document collection, financial analysis, credit underwriting, risk assessment, loan approval, documentation, closing, funding, and ongoing portfolio monitoring. Lenders evaluate the borrower’s financial health, cash flow, credit history, collateral, and repayment capacity before approving financing. After closing, lenders continue monitoring the loan and borrower to identify changes in risk and ensure compliance with loan terms.
What is commercial bank lending and how does it work?
Commercial bank lending is the process of providing businesses with financing for working capital, expansion, equipment, real estate, acquisitions, and other business needs. Banks evaluate the borrower’s financial performance, cash flow, creditworthiness, collateral, and ability to repay before approving financing. Commercial lending can include term loans, revolving lines of credit, asset-based lending, and commercial real estate loans, with terms structured around the borrower’s needs and risk profile.
What is commercial lending in banking?
Commercial lending in banking is the process of providing financing to businesses for needs such as working capital, expansion, equipment, acquisitions, inventory, and commercial real estate. Banks assess a business’s financial statements, cash flow, credit history, collateral, and repayment capacity before approving a loan. Common commercial lending products include term loans, lines of credit, commercial real estate loans, equipment financing, and asset-based lending.
What does a commercial lending contact center do?
A commercial lending contact center supports borrowers and lenders throughout the lending lifecycle by handling inquiries, lead qualification, application support, document follow-ups, loan status updates, and servicing requests. In the U.S., contact centers increasingly use AI, automation, and omnichannel communication to improve response times, streamline lending workflows, and deliver a more consistent borrower experience while maintaining compliance requirements.
What is the difference between a commercial loan and a business loan?
In practice they overlap. “Business loan” is the consumer-facing term and usually implies smaller, more standardised credit. “Commercial loan” is the industry term and covers the full range, including large negotiated facilities with covenants and ongoing reporting obligations.
How long does commercial loan approval take?
It varies by structure. A small secured line against an existing relationship can close in a few weeks. A commercial real estate mortgage or construction facility requiring appraisal, environmental review and committee approval commonly takes 45 to 90 days.
Who regulates commercial lending in the US?
It depends on the lender. National banks are supervised by the OCC, state non-member banks by the FDIC, state member banks by the Federal Reserve, and credit unions by the NCUA. Nonbank lenders are generally state-licensed. There is no single federal commercial lending regulator.
What is the difference between secured and unsecured commercial lending?
A secured loan is backed by specific collateral the lender can look to if the borrower defaults. An unsecured loan is not, and instead relies on cash flow and typically a personal guaranty. Unsecured credit generally carries a higher rate and tighter covenants.